Long before Davis Boabeng wrote a line of Swife's code, he watched the problem play out at home.
His mother is a businesswoman with interests across several sectors of Ghana's informal economy, and payday at her businesses looked the way it looks for thousands of Ghanaian enterprises: open MTN MoMo, send a transfer. Open Telecel Cash, send another. Switch to the banking app for the next one. Employees, suppliers, customer refunds, each payment keyed in individually, one recipient at a time, every single time.
"I always saw how stressed she was when she was performing such transactions," Boabeng recalls. "That ignited the will to find a solution."
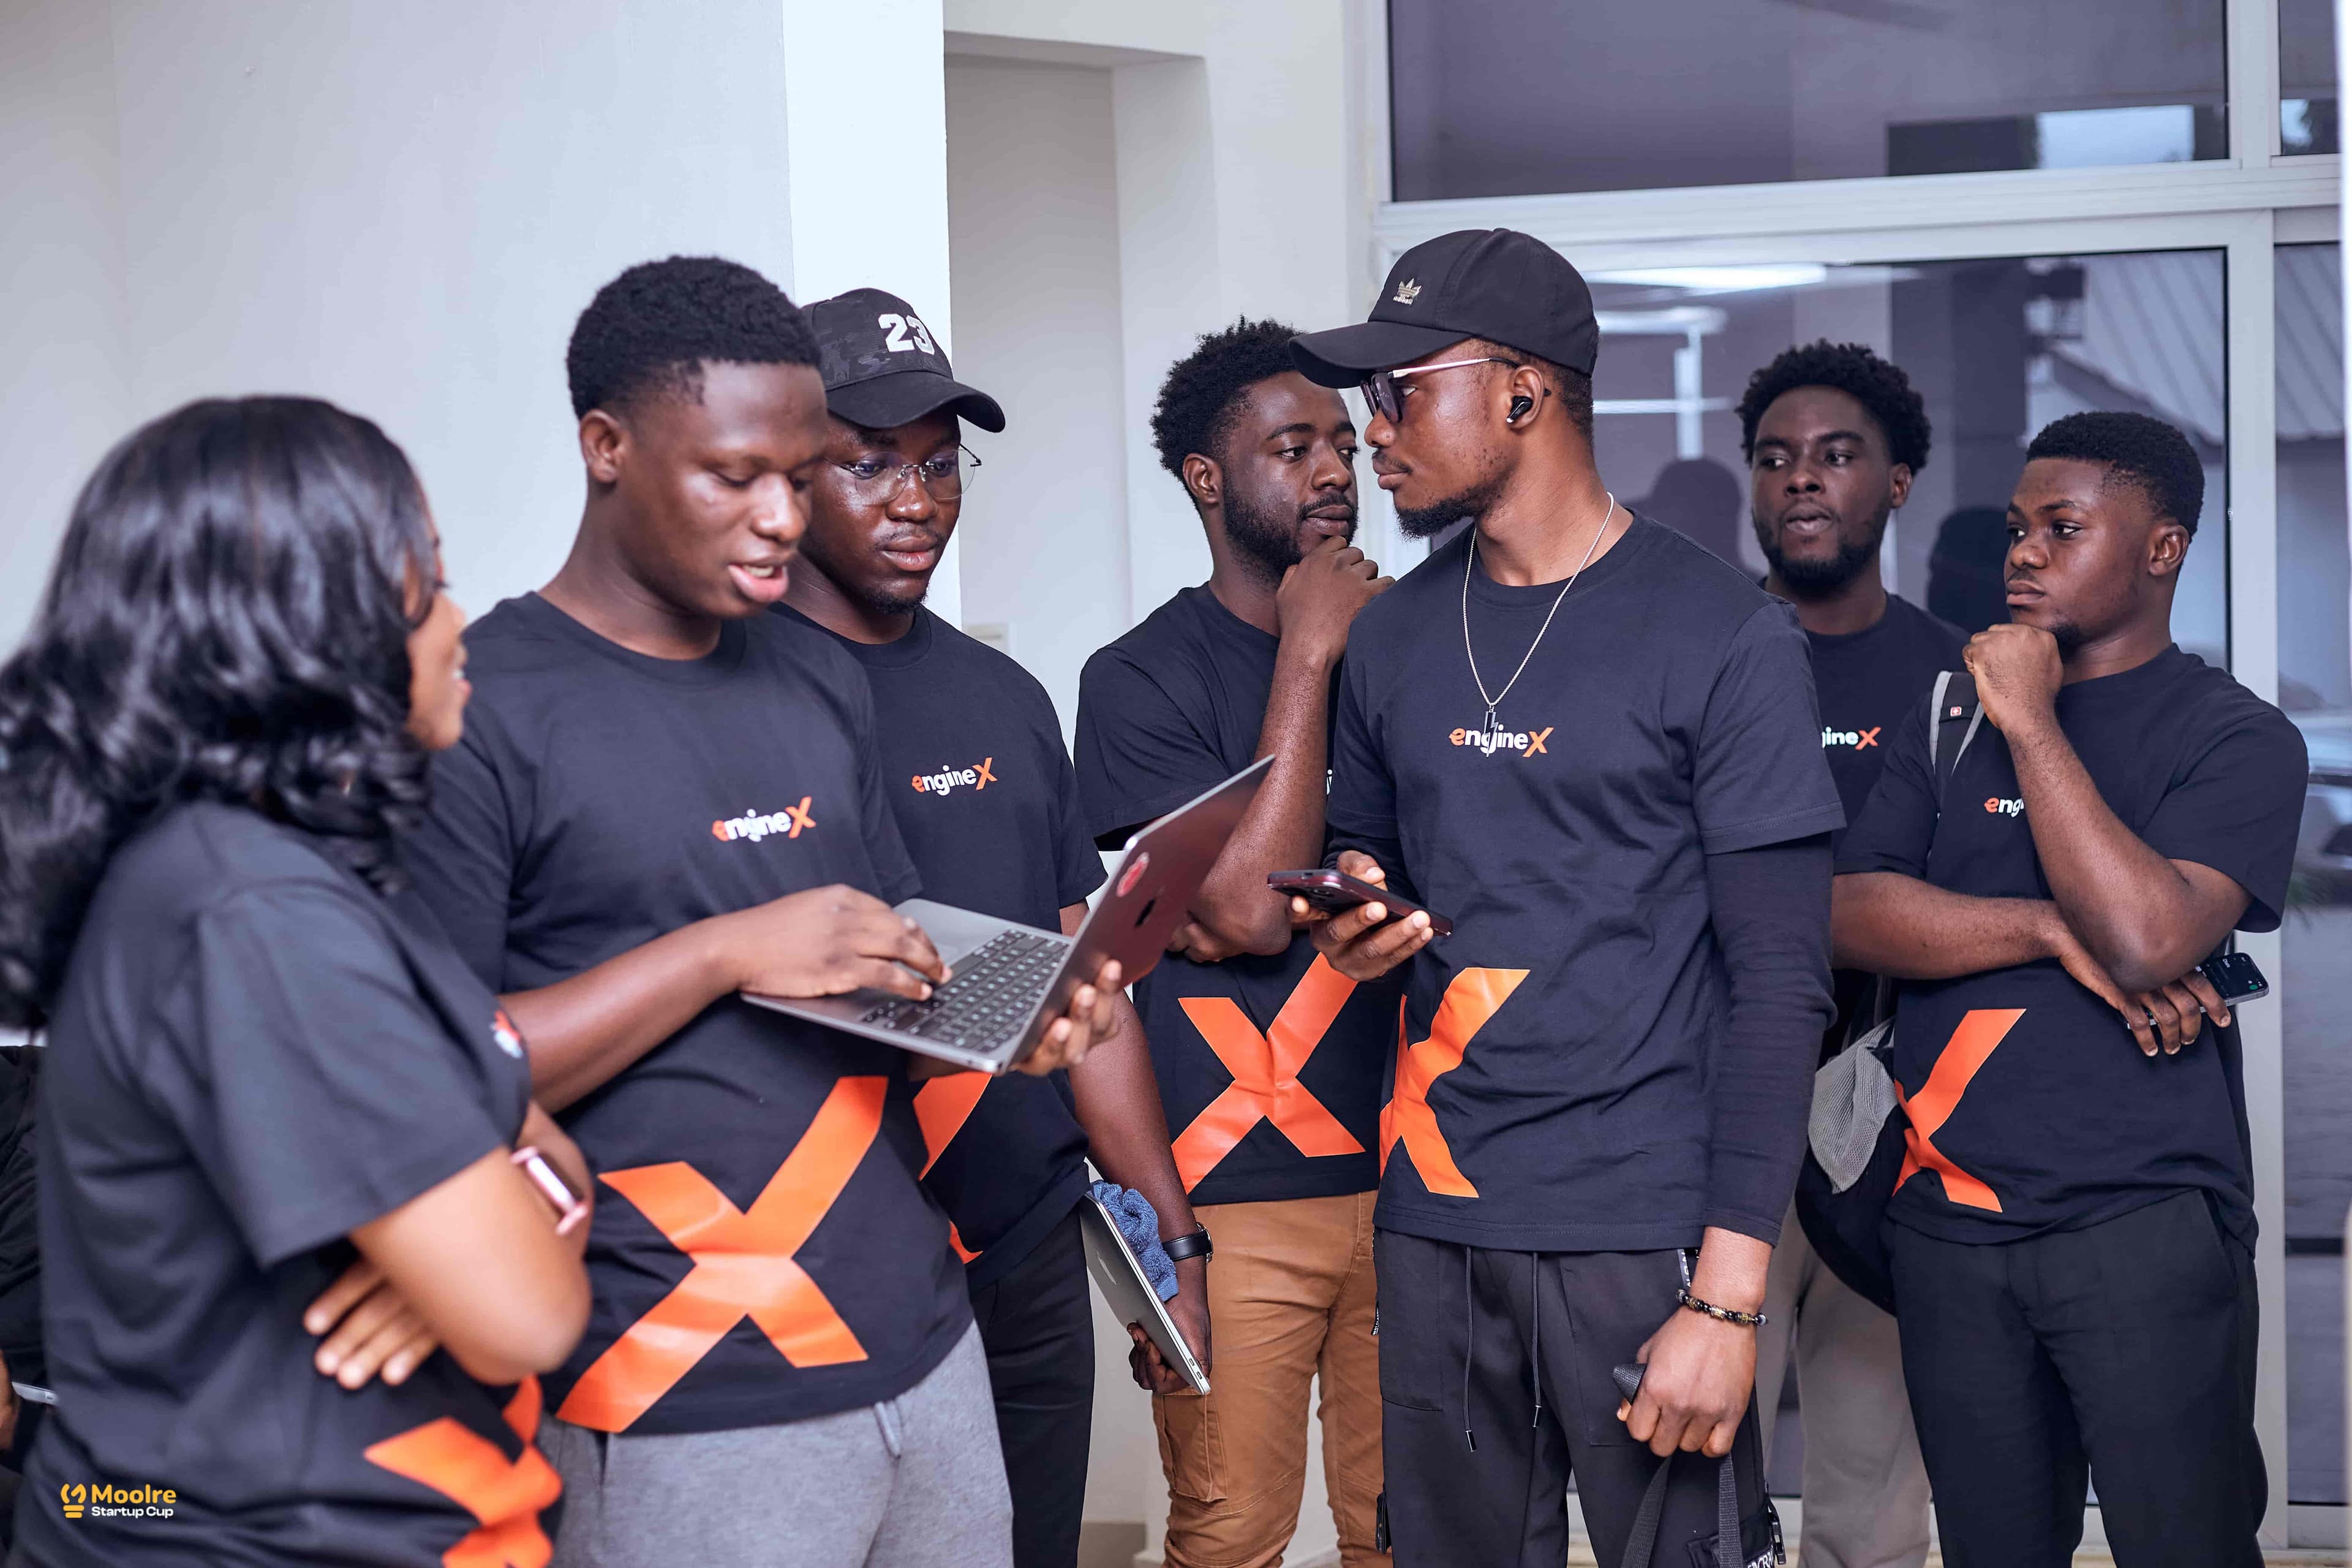
Today, Boabeng is co-founder and lead architect of Swife, a bulk payments platform for Ghanaian individuals and businesses, and one of the standout entries heading into the pitch stage of the 2026 Moolre Startup Cup, where it drew over 7,000 public votes during the community voting round.
A Problem Hiding in Plain Sight
The idea sat with the team for a while before they understood its scale. It was only when they went out and tested the market that the intensity of the problem became clear: most Ghanaian SMEs, and most individuals, simply have no unified way of sending money to several people at once.
It's a problem that hides in plain sight because everyone has normalized the workaround. Businesses run payroll by firing off mobile money transfers one by one, with no consolidated record of who was paid what. Families sending money home to several relatives repeat the same ritual. Susu groups paying out members, funeral and wedding committees settling contributions, all of it happens transfer by transfer, app by app, network by network.
Each individual payment is small friction. Multiplied across a payroll, a family, a community, it becomes hours of repetitive work, riddled with opportunities for error, with nothing to show for it afterwards but a trail of separate confirmation messages.
What Swife Does
Swife collapses all of it into a single action. A user uploads a list of recipients, a spreadsheet, a pasted text, even a messy note, and the platform takes over: it verifies every recipient by name against their registered wallet, detects each person's network automatically, and pays everyone across MTN MoMo, Telecel Cash, AT Money and every Ghanaian bank in one click.
The verification layer is the quiet centerpiece. Before a single cedi moves, every name on the list is matched against the wallet it's about to be sent to, closing off the wrong-number transfers that haunt mobile money users. Every recipient gets an instant SMS receipt. And for businesses whose customers or workers don't own smartphones, Swife reaches every rail through USSD as well.
Under the hood, the platform is built extensively on Moolre's infrastructure, its Wallet, Collections, Disbursements, USSD and SMS APIs, making it one of the deeper integrations in this year's Startup Cup field. Whether the list holds five people or five thousand, the flow doesn't change. As the team puts it: one click, every rail, everyone paid.
Built for Businesses — and for How Ghanaians Actually Move Money
What distinguishes Swife's framing is that it refuses to treat bulk payments as a purely corporate product. The same engine that runs an SME's payroll serves a family sending money home to several relatives, a susu group distributing its pot, or someone settling funeral and wedding contributions, the payments Ghanaians already make constantly, just done properly for the first time.
That breadth is deliberate, and it matches the scale of Boabeng's ambition. "We want to be able to take a huge chunk of the market share in this industry," he says. "We want Swife to be a household name, used by everyone and everywhere."
It's a bold target for a young team. But the underlying logic is hard to argue with: the one-at-a-time transfer is one of the most repeated actions in Ghana's digital economy, and almost nobody has built for the moment when one payment needs to become many. Swife is betting that once people experience payday, or contribution day, or payout day, as a single click, the old ritual of app-switching and number-punching will feel as dated as counting out cash.
Swife pitches live in the final stage of the Moolre Startup Cup, with winners announced at the Grand Finale on August 29, 2026.
Watch his full interview below:
Storyblocs by Brif, in collaboration with Insight Labs (Building Bytes). Presented in partnership with Moolre.